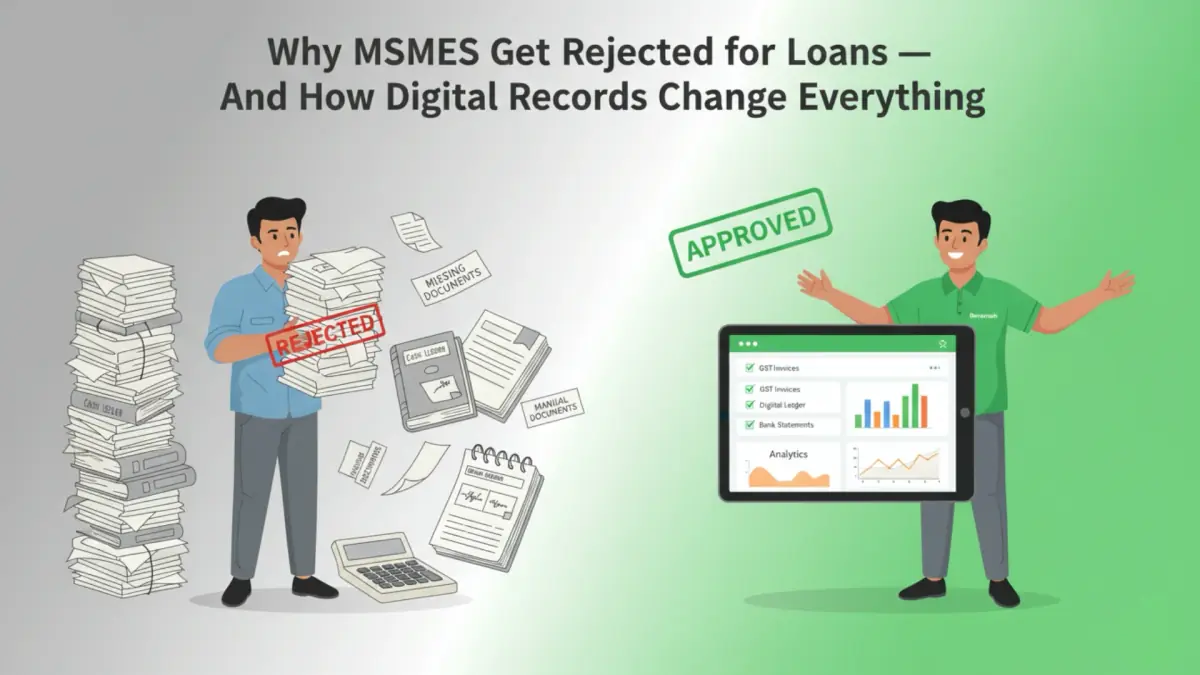
Why MSMEs Get Rejected for Loans And How Digital Records Change Everything
The Real Reasons Behind MSME Loan Rejections
Incomplete or Inconsistent Financial Records
Banks need clarity. Handwritten ledgers, mismatched invoices, or incomplete profit–loss statements push lenders away.
A kirana store owner from Mumbai shared: “My business was profitable, but when the bank asked for three years of financial statements, all I had were notebooks. They rejected my loan within a week.”
Lack of Proof of Cash Flow
Cash flow is the heartbeat of your business. Without documented daily sales, seasonal trends, payment cycles, or supplier credit, proving business stability becomes difficult.
Poor Inventory Management Documentation
Lenders assess inventory to understand operational efficiency. Without clear stock movement, purchase data, and turnover rates, banks can’t evaluate your business health.
Absence of Digital Footprint
In 2025, a business without digital presence appears risky. No digital payments, no online sales data, no visibility — banks lack the data they rely on for credit scoring.
Inability to Provide Real-Time Business Insights
Most MSME owners answer based on intuition, not data. Without clear information on top-selling products, profit margins, or customer patterns, lenders hesitate to trust projections.
Non-Compliance with GST and Tax Regulations
Irregular GST filings or mismatched tax returns are major red flags for lenders, signaling potential financial risk.
How Digital Records Transform the Lending Landscape
From Chaos to Clarity: The Digital Advantage
Digital record-keeping creates a real-time, comprehensive view of your business that banks understand and trust.
Automated Financial Tracking
Modern platforms automatically generate profit & loss statements, balance sheets, and cash flow reports—making loan applications smooth and professional.
GST Compliance Made Simple
Integrated GST billing ensures compliant invoices and on-time filings, eliminating one of the biggest loan rejection factors.
Real-Time Inventory Intelligence
Digital systems track stock movement and help banks assess working capital needs more accurately.
Data-Driven Decision Making
Analytics dashboards provide data on top-selling items, customer behavior, seasonal demand, and growth trends — turning your loan application into a compelling business case.
Building Your Digital Foundation
What to Look For in a Digital System
- Suitable for small and multi-location businesses
- Integrated with payments and shipping
- Generates bank-ready financial reports
- Affordable for micro-businesses
How Bharatrath Helps
Platforms like Bharatrath offer POS, inventory management, GST billing, analytics, and more — all designed for Indian MSMEs.
The Proof Is in the Numbers
Impact of Digital Records
- 3x higher loan approval rates
- Better interest rates and repayment terms
- Faster processing — weeks instead of months
- Eligibility for larger loan amounts
Beyond Loans: The Broader Benefits
Operational Efficiency
Digital systems reduce errors, eliminate paperwork, and free time for business growth.
Customer Experience
Modern billing and better inventory improve customer satisfaction and repeat sales.
Market Expansion
An online presence opens new customer bases beyond local boundaries.
Scalability
Digital infrastructure grows with your business — new products, locations, or B2B operations.
Taking the First Step
How to Begin Your Digital Journey
- Digitize billing and invoicing
- Implement real-time inventory management
- Create a professional online presence
- Integrate digital payment systems
- Review business reports regularly
The Bottom Line
Why Digitization Can’t Wait
Loan rejections aren’t always about business viability — they’re often about lack of visibility. Digital records build credibility, improve financial discipline, and unlock capital for growth.
The only question is: how quickly can you start?
Final Call to Action
Ready to transform your business with digital records? Explore MSME-ready digital tools at www.bharatrath.com.